Founding Quantitative AI Researcher · QuantLink AI

Quantitative research, rebuilt for machine intelligence.

I build systems that turn messy market data into decision-grade alpha: factor engines, ML strategy research, derivatives analytics, and NLP signals, taken from first dataset to production interface.

$ whoami
kanav_mehta · quantitative_researcher
focus   = factors | portfolio_construction | risk | agentic_research
stack   = python · sql · lightgbm · transformers · mcp
mode    = research → production, with audit trails
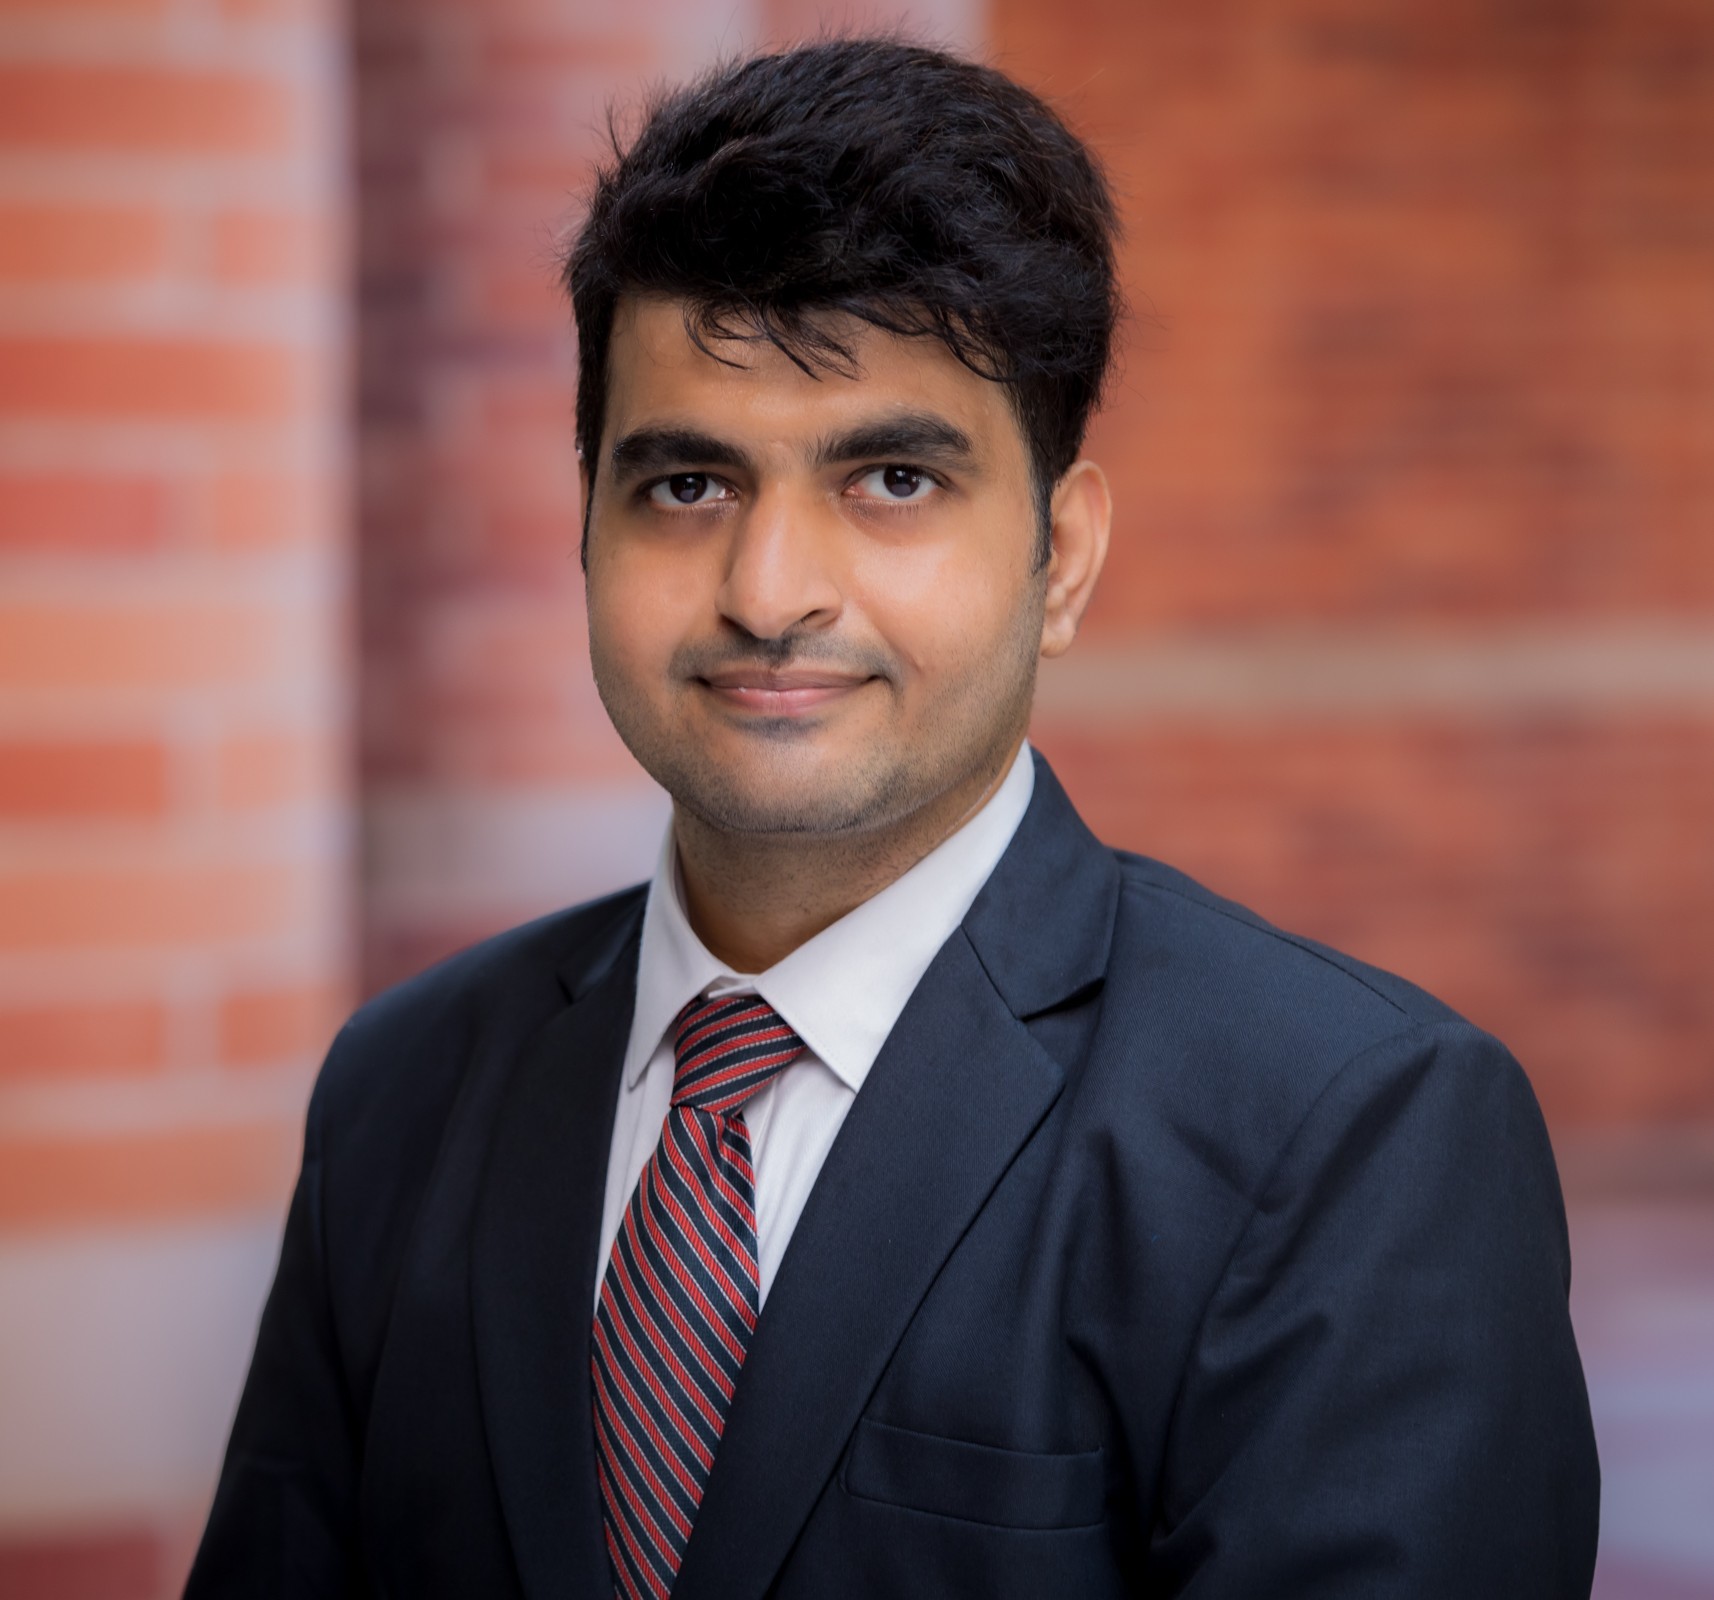
Portrait of Kanav Mehta

Kanav MehtaLos Angeles · UCLA MFE

3,545 stock universe covered by the factor research engine
40+ global alpha strategies designed across four regions
10+ analytics panels shipped end to end, research to UI
1st rank, WorldQuant BRAIN Alphathon · UCLA Anderson MFE

00 · Flagship

QuantFlow: an automated pipeline that produces desk-grade outlooks

Engine · Desk · Reports

From hypothesis to print-ready flagship report, with no manual glue work.

A survivorship-bias-free equity engine, an eleven-specialist analyst desk that debates and sizes each case, and a report generator rendering chart-led outlooks, all in one gold/teal visual identity. Latest outlooks: MSFT, GOOGL, META, and NVDA 12-month flagships, each argued across 20+ exhibits.

02 · Focus Areas

Three disciplines, one pipeline

Factors · Strategies · Language

QuantLink AI

Factor Engine

  • End-to-end factor research workflow across a 3,545-stock universe.
  • IC, rank correlation, OLS slope, R², monotonicity, and spread diagnostics in one pass.
  • Quintile and decile backtests with benchmark, sector, and market-cap analysis.

Systematic Trading

Strategy Lab

  • ETF and crypto strategies with sliding-window LightGBM, oscillators, liquidity, and macro-trend features.
  • Multi-region alphas across US, China, Europe, and UK markets.
  • Turnover control, transaction-cost-aware backtests, risk-adjusted quality first.

AI + Markets

NLP & Research UI

  • Transformers and knowledge graphs applied to filings, earnings calls, headlines, and macro communications.
  • Dashboards for screening, backtesting, alpha review, and risk monitoring.
  • Complex analytics translated into interfaces analysts can scan under pressure.

03 · Experience

Analytics → Quant Research → Quantitative AI

2017–Present

Apr 2026–NowRemote · Minneapolis HQ

Founding Quantitative AI Researcher

QuantLink AI

Building an MCP-based agentic quant research platform (AI agents that research, evaluate, and refine strategies through desk-grade backtesting, portfolio construction & optimization, and risk-model attribution) alongside constrained long-only/long-short construction with multi-factor exposure monitoring. Shipped a point-in-time market-data platform, a SQL-native backtester, AutoML Workbench, Notebook Dashboards with a self-checking notebook AI agent, an options workspace, and a 1,139-operator typed catalog, with 517 merged pull requests and 1,059 code reviews to date.

Current
Jun–Sep 2025Tampa, FL

Quantitative Researcher

Quanta Ventures

End-to-end Python ML pipeline for Bitcoin, Ethereum, and QQQ strategies: sliding-window LightGBM linear trees, walk-forward validation, live paper trading net of transaction costs with Sharpe above 1.5. Partnered with traders on equity-index, crude-oil, and precious-metals futures research.

ML Strategies
Feb–Jun 2025Remote

BRAIN Research Consultant

WorldQuant

Engineered 40+ intraday and medium-frequency strategies from fundamental, analyst, short-interest, news, price-volume, and options data across US, China, Europe, and UK markets.

Alpha Research
Dec 2020–Jul 2024New York

Senior Quantitative Research Associate

Wolfe Research

Built NLP factors, risk-neutralized models, intangible-asset research, macro risk-exposure frameworks, and analyst-facing dashboards for alpha discovery and portfolio context.

NLP · Risk
2017–2020India

Analytics Consultant · Business Analyst

ZS Associates · Udaan

Observational studies on claims and EHR data, survival analysis, anomaly detection, revenue forecasting, and operational collections optimization. The statistical foundation for everything since.

Statistics

04 · Selected Work

Research you can open

Full index → /projects

Agentic Research★ Flagship

QuantFlow

An agent desk that researches, debates, and sizes a single-name case, then prints it. Eleven specialists, a recorded bull/bear debate, and a risk-manager veto before any outlook ships.

11specialist agents 27engine tools MCPagent tools dark+lightreports
Agentic Research
Factor Research

Single-Factor Modeling · QuantLink AI

Cross-sectional factor dashboard: ranking, diagnostics, buckets, risk, and backtest review in one workflow.

3,545stocks 10+panels IC + OLSdiagnostics Q / Dbuckets
Factor InvestingBacktesting
QuantLink AI · ML Platform

AutoML Workbench

No-code training, ranking, explanation and deployment of many ML models, with leakage-safe purged walk-forward validation and holdout Rank IC leaderboards.

5problem types 1Mrows per table 31plain-language errors 4engine releases
scikit-learn · XGBoost · LightGBMFastAPI · Redis/RQNext.js
QuantLink AI · Analytics Product

Notebook Dashboards

One click from Python research notebook to interactive dashboard: typed inputs, scheduled reruns, and server-side pivots over up to 50M rows.

50Mrows per table 9typed inputs 6codebases 7-tabstock page rebuilt
DuckDBNext.jsFastAPI
QuantLink AI · Data Platform

Point-in-Time Market Data Platform

Survivorship-free market data: a universe that keeps delisted companies, ~180M rows of calculations at exact parity, and a replayable dbt lakehouse.

180Mcalc rows rebuilt 1,442columns at exact parity 107.6Mrow backfill 20bulk datasets
ClickHouse · DagsterdbtPoint-in-Time Data
QuantLink AI · Backtesting

SQL-Native Backtester

Backtesting written entirely as dbt SQL on ClickHouse: no Python loop, look-ahead blocked by construction, P&L reconciled to every trade.

14dbt gold models 7,184trades simulated 81/81build checks green Weeklyproduction rebuild
dbtClickHouseSQL
QuantLink AI · AI Agents

Notebook AI Agent

An AI agent that edits research notebooks against a live kernel and checks every edit before it applies, on an isolated, production-grade runtime.

725operators searchable 115warehouse datasets 5model tools 477focused tests
LLM tool callingPython / JupyterFastAPI
AI / NLP

FOMC Sentiment Toolkit

FinBERT-FOMC suite released as a package and CLI: policy-regime tone, novelty scores, walk-forward validation, and sign-signal backtests.

FinBERTfine-tuned Noveltyscore LightGBMSPX & spreads Walk-forwardvalidation
NLPMacro
Options & Rates

American Options & Securitized Products

Numerical methods for early exercise, barriers, MBS, and G2++ rate models (lattices, LSMC, FDM, Monte Carlo).

LSMCearly exercise FDMgreeks G2++rates MBSvaluation
Monte CarloDerivatives
Agentic Research

Agentic Alpha Engine

End-to-end alpha engine for US equities on public data, designed to be driven by any MCP-capable AI agent: ingest, transform, backtest, optimize. Now at v0.5.0 with a survivorship-bias-free point-in-time universe.

25+MCP tools dbt+DuckDBtransform 170+factors built in vectorbtbacktests
Agentic ResearchPortfolio Optimization
Trading Systems

Stat Arb Optimization & Risk

RMT-denoised and shrinkage covariance estimation with transaction-cost-aware convex optimization for a copula-based US equity pairs strategy.

RMTdenoised Shrinkagecovariance Cost-awareconvex opt Copulapairs
Stat ArbRisk Analytics
Market Structure

MAG7 Concentration Effects

IAQF 2025 research: did SMB factor behavior decouple once concentration moved into mega-cap winners?

IAQF2025 SMBfactor MAG7regime Crowdingrisk
FactorsConcentration
Derivatives · Portfolio Research

LEAPS as Stock Substitutes

Long/short equity built on LEAPS instead of stock: Black-Scholes on escrowed spot, a calibrated IV proxy, and a daily-accounting engine that reprices exercise, expiry, and ruin on public data only.

V0–V3portfolio variants V1–V4validation gates DailyNAV reconciliation No-lookaheadsignal audit
LEAPSLong/ShortBacktesting
Factor Research · AI

AI Exposure Factor Suite

Two market-implied AI return factors built point-in-time from ETF baskets: AI Theme (AUM-weighted, ex-semiconductors) and AI Infrastructure. Together they form the base for measuring firm-level AI exposure with Fama-French controls.

2AI factors AUM-weightedbaskets Point-in-timeconstruction FFcontrols
AI FactorsETFsRisk Exposure
Portfolio Construction

MAPO: Multi-Asset Optimizer

One optimization API across equities, crypto, futures, FX, and treasuries, unifying PyPortfolioOpt, skfolio, and Riskfolio-Lib behind native solvers: exact SOCP max-Sharpe under asset-class caps and turnover, CVaR LP, HRP/HERC, Black-Litterman, and a no-lookahead walk-forward backtester.

5asset classes SOCPmax-Sharpe CVaRLP Walk-forwardbacktests
OptimizationConvexRisk Models
Agentic Research · Reporting

report-forge

MCP-driven report engine that turns Markdown and chart PNGs into publication-grade PDF, HTML, and DOCX, with 19 templates, native Exhibit numbering, and mechanical quality gates that refuse to ship a bad exhibit. Renders QuantFlow's flagship outlooks.

19templates 4output formats 40+MCP tools Qualitygates
Agentic ResearchTypstQuarto
Agentic Research · Memory

Spark-MCP

Creativity and institutional-learning MCP server for quant research. Spark remembers everything a team has tried (failures included), deflates significance for the full trial count, and maps the unexplored corners of research space.

33MCP tools DSRsignificance gates MAP-Elitesexploration Replaygated skills
MCPResearch MemoryDeflated Sharpe
Prediction Markets · NLP

Kalshi Mentions Pricing

Fair-value engine for Kalshi's "Mentions" contracts: will a word be said, and how many times. A hurdle model pairs shrunk Beta-Binomial base rates with a truncated negative-binomial repetition process, plus live Gamma-Poisson updating mid-event and walk-forward backtests against the base rate.

Hurdlemodel Liveupdating Walk-forwardbacktests FastAPI+Mantinedashboard
Prediction MarketsNLPProbability

05 · Research & Writing

Notes, papers, and tearsheets

Working out loud

06 · Capabilities

The stack behind the research

Quantitative Finance

Factor investing, cross-sectional analysis, derivatives pricing, fixed income, statistical arbitrage, portfolio construction, and risk diagnostics.

ICSharpeFama-FrenchMBSBloombergFactSetCapital IQ

Machine Learning & Applied AI

LightGBM, Elastic Net, transformer models, FinBERT, anomaly detection, and model validation under noisy market data, plus research agent workflows built on MCP tool servers.

LightGBMTransformersFinBERTMCPAgents

Data Engineering

Python, R, SQL, C++, Git, AWS, Linux; point-in-time data discipline, structured pipelines, APIs, and research reproducibility.

PythonSQLRC++

Product Systems

Interactive dashboards, chart design, stateful controls, screeners, backtest explorers, and analyst workflows built for repeated use.

DashboardsScreenersAnalytics UX

07 · Education

Engineering roots, finance depth

UCLA Anderson School of Management

Master of Financial Engineering

2024–2025 · GPA 3.93 / 4.0

  • 1st Rank, WorldQuant BRAIN Alphathon · VP of Careers
  • IAQF 2025 co-author: MAG7 concentration research
  • Coursework: Computational Methods, Quantitative Asset Management, PhD-level Financial Economics, Statistical Arbitrage, Credit Markets

IIT Roorkee

B.Tech, Civil Engineering

2013–2017 · KVPY Scholar

  • KVPY Scholarship, a national science research fellowship
  • Quantitative and computational foundation in mathematics, mechanics, and programming

Contact

Let's talk factors, models, and markets.

Los Angeles · UCLA Anderson MFE · research experience at QuantLink AI, Quanta Ventures, WorldQuant, and Wolfe Research.