Factor Research · AI

Measuring the market's AI exposure, from the market itself.

Two daily return factors distilled from ETF flows: an AI Theme factor and an AI Infrastructure factor, built point-in-time so firm-level exposure estimation avoids look-ahead bias.

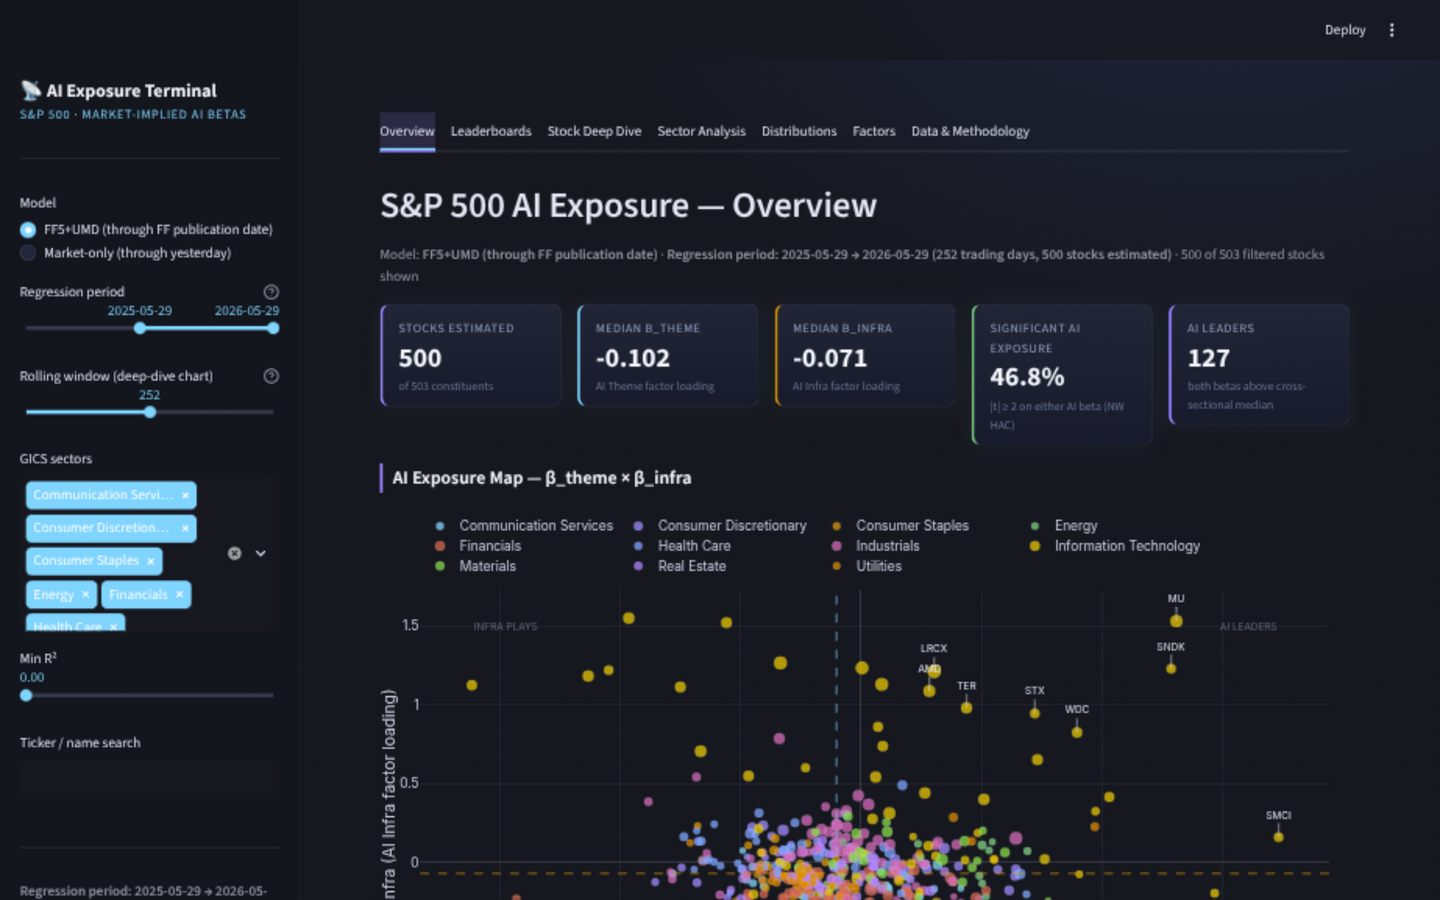
S&P 500 AI exposure dashboard showing beta distributions for AI theme and infrastructure factors
Trailing 252-day regressions with Newey-West t-stats: β distributions for both AI factors and the theme-vs-infrastructure scatter, as of the last trading day.

Two factors, cleanly separated.

  • F_AITheme: an AUM-weighted basket of AI-focused ETFs, excluding semiconductors; the "use of AI" exposure.
  • F_AIInfra: semiconductor and AI-infrastructure ETFs, the "picks and shovels" exposure.
  • Eligibility and bucket assignments live in versioned classification files, so the factor definition is auditable rather than ad hoc.

Point-in-time or it didn't happen.

  • Raw data lands untouched, then moves through processed, reference, and factor layers with QC diagnostics at each step.
  • Factor returns are checked against Fama-French controls; what survives net of market, size, value, and momentum is the AI signal.
  • Rolling betas from these factors become the inputs for firm-level AI exposure estimation in the next part of the program.

Exposure estimation needs a valid factor first.

  • Everyone claims AI exposure; almost nobody measures it with a return-based, point-in-time factor.
  • ETF flows are the market's own portfolio of AI claims. Using them as the factor keeps the definition market-implied rather than keyword-driven.
  • The suite is Part 1 of a longer program: firm-level AI betas, then factor portfolios tilted by measured exposure.